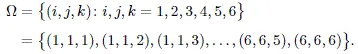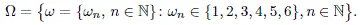This is an introduction to stochastic integration and stochastic differential equations written in an understandable way for a wide audience, from students of mathematics to practitioners in biology, chemistry, physics, and finances. The presentation is based on the naïve stochastic integration, rather than on abstract theories of measure and stochastic processes. The proofs are rather simple for practitioners and, at the same time, rather rigorous for mathematicians. Detailed application examples in natural sciences and finance are presented. Much attention is paid to simulation diffusion processes. The topics covered include Brownian motion; motivation of stochastic models with Brownian motion; Itô and Stratonovich stochastic integrals, Itô's formula; stochastic differential equations (SDEs); solutions of SDEs as Markov processes; application examples in physical sciences and finance; simulation of solutions of SDEs (strong and weak approximations). Exercises with hints and/or solutions are also provided.
The main notion of probability theory is a probability space (Ω,
, P) consisting of any set of elementary events (or outcomes) Ω, a system of events
, and probability measure P. Though these objects form an unanimous whole, we shall try to consider them separately.
Sample space Ω is any non-empty set. Its elements are interpreted as all possible outcomes of an experiment (test, monitoring, phenomenon, and so on) and are called outcomes or elementary events. They are often denoted by letter ω (possibly with some index(es)). Let us consider some examples.
EXAMPLE 1A. Suppose that our experiment involves throwing a die once. Usually, we are only interested in the number of dots, and so all possible outcomes can be described by the sample space Ω = {1, 2, 3, 4, 5, 6}. Naturally, the outcome of the experiment “the number of dots that appeared on top is five” is represented by the simple event ω = 5.
EXAMPLE 1B. Consider the more complex experiment of throwing a die thrice. It can be described by the sample space consisting of all triples (i , j, k) of the natural numbers from 1 to 6 (the number of such triples is 63 = 216):
EXAMPLE 1C. If a die is thrown an unknown (in advance) number of times (for example, until six dots appear three consecutive times or until we are tired of throwing), it is convenient to consider the abstract model with unlimited number of dice throws. An outcome of such an “experiment” can be described by a sequence ω= {ωn} = {ω1,ω2,..}, the elements ωn of which are arbitrary natural numbers from 1 to 6. Thus, in this case, the sample space is the set of all such sequences:
EXAMPLE 2A. Suppose that we decided to measure the outdoor temperature. An outcome of the “experiment” could be the temperature at a fixed moment in time. Since, practically, the temperature cannot be lower than (say) −60°C and higher than +60°C, for this experiment, we can consider the sample space Ω = [− 60, 60]. However, it is often more convenient not to define any reasonable bounds for the temperature (perhaps we measure the temperature in Mars or in the center of the Sun) and take Ω =
.
EXAMPLE 2B. Let us measure the outdoor temperature each hour for the whole day. Then the outcome of the experiment is a set of 24 numbers meaning the temperatures at time moments t = 1, 2,… , 24, and a...
Table of contents
Cover
Title Page
Copyright
Preface
Notation
Chapter 1: Introduction: Basic Notions of Probability Theory
Chapter 2: Brownian Motion
Chapter 3: Stochastic Models with Brownian Motion and White Noise
Chapter 4: Stochastic Integral with Respect to Brownian Motion
Chapter 5: Itô's Formula
Chapter 6: Stochastic Differential Equations
Chapter 7: Itô Processes
Chapter 8: Stratonovich Integral and Equations
Chapter 9: Linear Stochastic Differential Equations
Chapter 10: Solutions of SDEs as Markov Diffusion Processes
Chapter 11: Examples
Chapter 12: Example in Finance: Black–Scholes Model
Chapter 13: Numerical Solution of Stochastic Differential Equations
Chapter 14: Elements of Multidimensional Stochastic Analysis
Solutions, Hints, and Answers
Bibliography
Index
Trusted by 375,005 students
Access to over 1.5 million titles for a fair monthly price.
Study more efficiently using our study tools.
Frequently asked questions
Yes, you can cancel anytime from the Subscription tab in your account settings on the Perlego website. Your subscription will stay active until the end of your current billing period. Learn how to cancel your subscription
No, books cannot be downloaded as external files, such as PDFs, for use outside of Perlego. However, you can download books within the Perlego app for offline reading on mobile or tablet. Learn how to download books offline
Perlego offers two plans: Essential and Complete
Essential is ideal for learners and professionals who enjoy exploring a wide range of subjects. Access the Essential Library with 800,000+ trusted titles and best-sellers across business, personal growth, and the humanities. Includes unlimited reading time and Standard Read Aloud voice.
Complete: Perfect for advanced learners and researchers needing full, unrestricted access. Unlock 1.5M+ books across hundreds of subjects, including academic and specialized titles. The Complete Plan also includes advanced features like Premium Read Aloud and Research Assistant.
Both plans are available with monthly, semester, or annual billing cycles.
We are an online textbook subscription service, where you can get access to an entire online library for less than the price of a single book per month. With over 1.5 million books across 990+ topics, we’ve got you covered! Learn about our mission
Look out for the read-aloud symbol on your next book to see if you can listen to it. The read-aloud tool reads text aloud for you, highlighting the text as it is being read. You can pause it, speed it up and slow it down. Learn more about Read Aloud
Yes! You can use the Perlego app on both iOS and Android devices to read anytime, anywhere — even offline. Perfect for commutes or when you’re on the go. Please note we cannot support devices running on iOS 13 and Android 7 or earlier. Learn more about using the app
Yes, you can access Introduction to Stochastic Analysis by Vigirdas Mackevicius in PDF and/or ePUB format, as well as other popular books in Mathematics & Functional Analysis. We have over 1.5 million books available in our catalogue for you to explore.